Workers Pay the Price: The Wider Supply Chain Impact of Middle East Instability
Instability in the Middle East is increasingly being reflected in global s
upply chain disruption, not as a single shock event, but as a set of interconnected pressures moving through energy systems, labour structures and manufacturing networks.
Critical energy routes, mobile labour forces and export manufacturing systems are tightly coupled, meaning disruption in one area can translate into operational pressure in another, resulting in significant shifts in risk across global sourcing ecosystems.
Energy routes and downstream production pressure
A significant proportion of global oil and LNG trade moves through a small number of maritime chokepoints, including the Strait of Hormuz. This creates a structural dependency within global energy flows, particularly for energy-importing manufacturing economies.
When geopolitical tension increases in these corridors, the effects tend to appear downstream in industrial systems rather than as immediate supply interruption. These include tighter energy availability, higher input cost volatility, and fluctuating production conditions in energy-intensive sectors such as textiles, ceramics and transport manufacturing.
The most material impact is often not total disruption, but inconsistency in energy supply conditions, which feeds directly into variability in production planning and output stability, with implications for workers in affected regions through shifts in working conditions and income stability.
Migrant workers face heightened risk in Gulf economies
Across many Gulf Cooperation Council economies, a large proportion of private sector activity is supported by migrant labour, particularly in construction, logistics, hospitality and manufacturing-adjacent services.
This creates a structurally concentrated workforce model, where economic activity is closely linked to cross-border labour mobility and employment frameworks tied to sponsorship-based systems.
In periods of geopolitical instability, this structure can become more sensitive due to constraints on mobility, changes in residency conditions, and operational pressure on sectors dependent on continuous labour availability. These dynamics increase exposure for foreign migrant workers in GCC economies, particularly where mobility and employment conditions are constrained within sponsorship-based labour systems.
Energy dependency risks in Asian manufacturing hubs
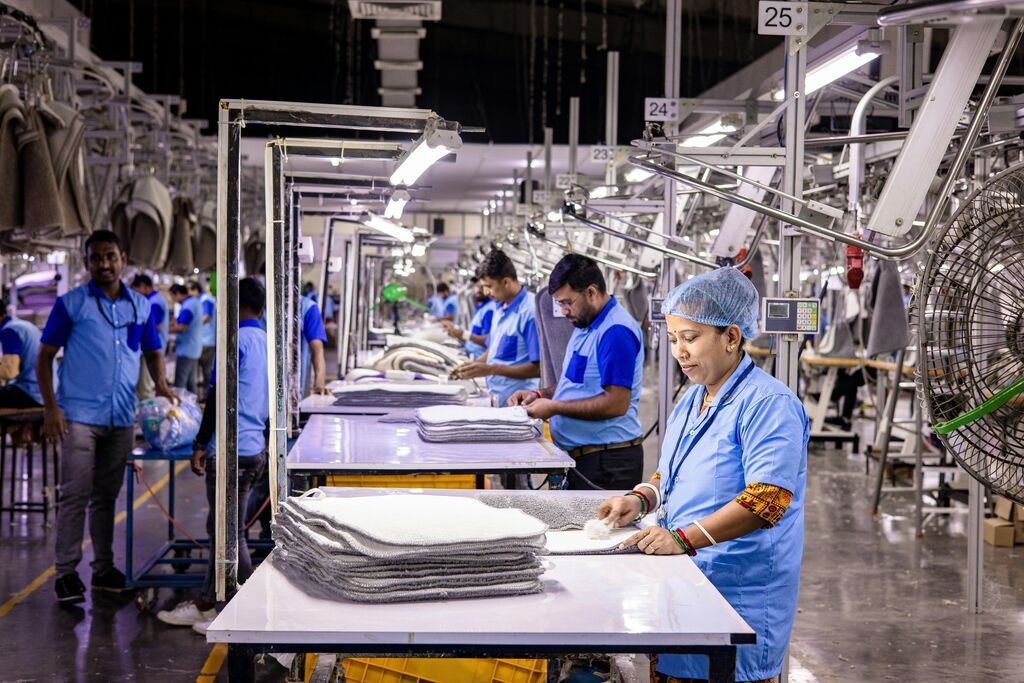
Energy and labour pressures in the Middle East are increasingly reflected in Asian manufacturing hubs that are closely integrated into global export networks. These effects are not isolated events, but part of a broader transmission of system stress across interconnected production regions.
In practice, this is visible through several recurring patterns:
- Reduced textile production and factory operating hours in Bangladesh linked to LNG dependency.
- Factory shutdowns and workforce disruption in India’s gas-dependent ceramic manufacturing sector.
- Rising fuel costs in Sri Lanka affecting transport workers and informal labour markets.
- Increased pressure on workers through reduced hours, income instability, and fluctuating production conditions.
How disruption moves through supply chains
The current environment highlights how global supply chains function as interconnected systems rather than linear networks.
Energy corridors, labour structures and manufacturing hubs are increasingly interdependent. As a result, geopolitical instability in one region can be transmitted through multiple layers of global production, affecting not only cost and availability, but also increasing social risks across entire sourcing ecosystems.
Understanding this pattern is less about predicting disruption and more about recognising how concentration within global systems amplifies the movement of risk across borders.
Related Posts
Discover more insights from our blog.
Labour risk after the US midterms: build the strategy first
Labour risk in US supply chains does not depend on new due diligence law. After the midterms, companies will need evidence of what their programmes achieve.
The UK's due diligence law: what's been announced and what's still open
The UK is moving from modern slavery reporting to mandatory due diligence. What has been announced and what businesses can do now.
Simplified, but intact: what Omnibus I now means for CSRD and CSDDD
Omnibus I is now law. Far fewer companies are in scope, but the duty to address supply chain harm remains.